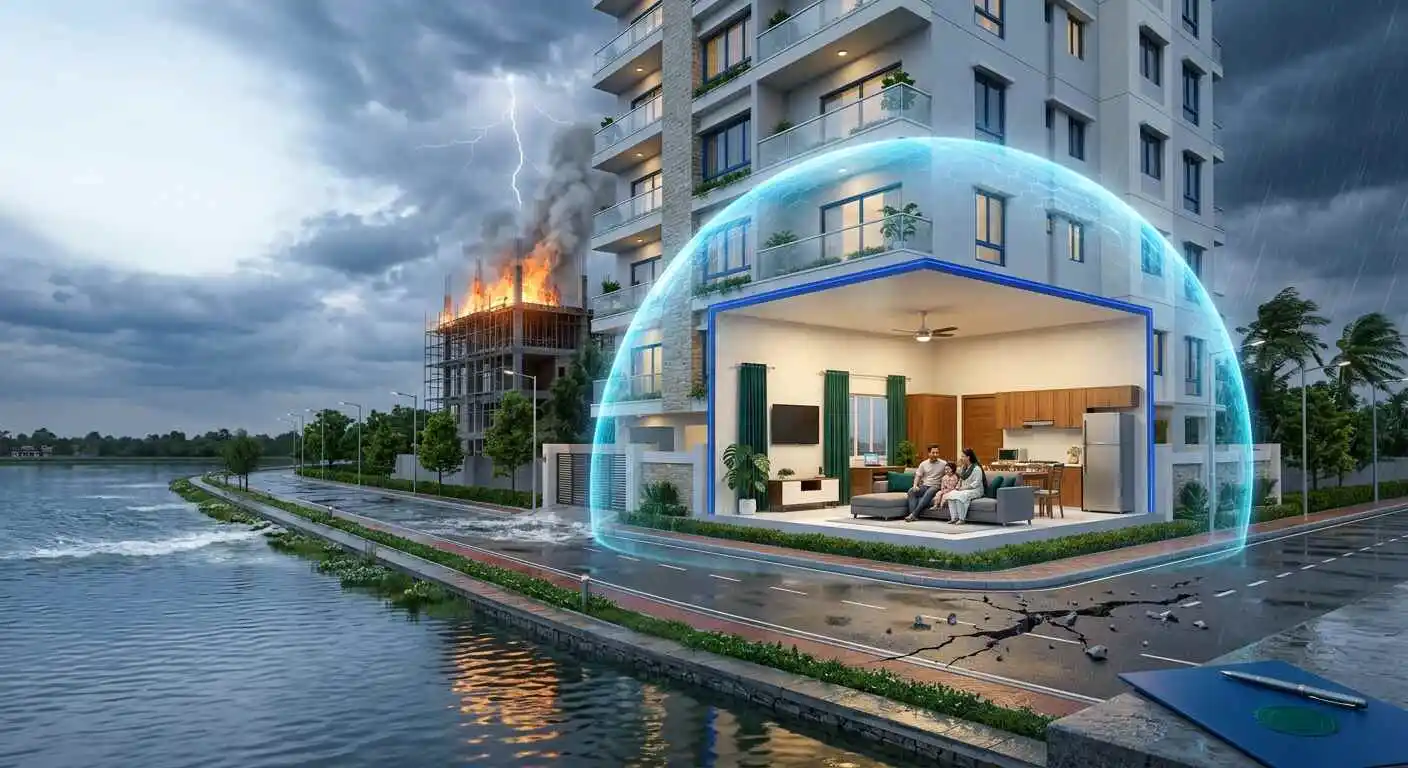
Flat insurance in Bangladesh starts with a fire policy, and any trusted real estate developer like PDL will tell you the same. A basic fire policy covers fire and lightning, and often explosions.
It does not cover cyclones, storms, or floods. Earthquake damage is left out too unless you add it, so ask your insurer to add earthquake and flood cover.
Many owners hear "fire insurance" and assume it protects against everything that can go wrong in Dhaka or Chattogram. It doesn't.
If you are buying a flat, treat a standard policy as the base layer. The protection against floods, cyclones, riots, and earthquakes comes from add-ons, which insurers call endorsements.
What Does Flat Insurance Cover, and What Does It Leave Out?
Flat insurance in Bangladesh usually refers to a fire policy for an apartment, extended to cover additional hazards.
You can insure two things: the structure and the contents. Decide on each one separately, because they follow different rules.
Structure: the parts that stay if you move out
Structure means the flat itself. Think of walls, flooring, fitted cupboards, permanent fixtures, and interior finishes.
Contents: everything you can carry out
Contents means furniture, appliances, TVs, computers, clothing, bedding and kitchenware. Many people insure only this part, then discover the flat's own fittings were never covered.
Structure, contents or both
You can buy each part separately, or ask for both in a single schedule. Either way, each part needs its own sum insured and its own wording.
| Cover type | What it protects | What to ask for |
| Structure (flat owner cover) | Walls, flooring, fitted cupboards, permanent fixtures and interior finishes | Reinstatement value as the sum insured |
| Contents | Furniture, appliances, electronics, clothing and kitchenware | A separate sum insured and a written inventory |
| Structure and contents together | Both parts of your home | Each part listed with its own sum insured |
The basic fire policy
Green Delta's fire insurance page lists fire, lightning and domestic explosion as the basic cover. Aircraft damage, storm, flood, riot and strike, and landslide can be added for an extra premium.
For homes and small premises, a gas cylinder explosion in the kitchen is typically covered. Industrial boiler bursts are a different matter and not relevant to a flat.
Insurers also apply the idea of proximate cause. They look at the direct, main trigger of the damage. If lightning hits the roof and starts a fire, lightning is the proximate cause and a standard policy responds.
If a storm causes a flood that then leads to an electrical fault, the claim becomes more complicated.
A real example of contents cover
Nibedita, a women's insurance product sold through Eastern Bank (EBL), shows how contents cover can work in practice.
It is mainly a personal accident plan, not a home policy, but its Regular and Plus packages also pay for loss of or damage to household goods and personal effects from fire, lightning, riots, storms, typhoons, floods, cyclones, and earthquakes.
The cap is 25% of the sum insured. For example, on a BDT 10 lakh sum insured, household goods are covered up to BDT 2.5 lakh.
So contents cover can be a fixed share of a larger sum, and you should always ask how the limit is set.
Peril by peril
The table below shows which common risks a basic fire policy usually covers and which ones need an add-on. Use it as a checklist when you compare quotes.
| Peril | Usually covered in a basic fire policy | Usually an add-on |
| Fire | Yes | No |
| Lightning | Yes | No |
| Gas or domestic explosion | Typically yes | No |
| Flood and cyclone | No | Yes |
| Storm | No | Yes, depending on insurer |
| Earthquake and landslide | No | Yes |
| Riot, strike and malicious damage | No | Yes |
| Theft and burglary | No | Separate cover, often with a forced-entry condition |
Insurers differ, so don't assume every policy matches the table. Read the schedule you are actually offered.
So, does fire insurance cover earthquake? Not on its own. You need the earthquake add-on written into your schedule.
Do You Still Need Cover When You Already Own the Flat?
Yes, in most cases. Owning the flat means you carry the loss, and fire is the clearest reason.
Fire insurance for a flat in Bangladesh costs little next to the bill for a gutted home.
The numbers explain why. Bangladesh recorded 27,059 fire incidents in 2025, about 75 a day, according to the Fire Service and Civil Defense.
In 2025, 8,705 of Bangladesh's recorded fires, about 32%, were in residential buildings. A year earlier, residential fires numbered 7,131 and made up 26.74% of the total.
The causes are ordinary, such as faulty wiring, kitchen accidents, and gas leaks. You can reduce these risks, but you cannot remove them. Insurance covers what prevention cannot.
Cash buyer vs. loan buyer: who is required to buy flat insurance?
A cash buyer is not forced to insure. The choice is yours, and so is the risk. If a fire gutted the flat, you would pay for repairs, replacement furniture, and temporary housing yourself.
A loan buyer often has no choice.
Banks such as BRAC Bank and DBH commonly require property insurance on a home loan.
For example, HSBC's home loan page once listed property insurance against fire, earthquake, flood and cyclone as a security document. HSBC has since wound down its retail banking business in Bangladesh (announced in July 2025), so treat this as an example of past lender practice rather than a current offer.
If you have a mortgage, ask your lender what cover it requires and whether the policy must be named on it.
Our guide to a home loan for a flat in Bangladesh covers the loan side in more detail. Meeting the lender's minimum may still leave you with a gap.
A policy that satisfies the bank may cover the structure but say nothing about your furniture, or leave out flood.
Flat investors and renters: what should each person insure?
The same logic applies if you bought the flat as an investment in Bangladesh real estate.
An empty or rented flat still burns, and a gap in cover still lands on you.
If you rent instead, the structure belongs to your landlord. Your own belongings are the part to protect, and our tips for first-time renters in Dhaka explain what else to check before you sign.
Who Insures the Building, and Who Insures Your Flat?
Ask the developer or the owners' association whether a common policy exists, and check what the service charge covers.
This is the question most flat owners never ask. In an apartment building, the structure is shared, and the owners' association or the developer may handle common areas such as the roof, stairs, lifts, and outer walls.
The answer matters whether you live in an apartment or a condominium, and our comparison of apartment vs condominium living in Bangladesh shows how ownership of shared areas differs. Ask three things.
- Does a common policy exist for the building and common areas?
- Which perils does it cover, and does it include earthquake and flood?
- Who pays the premium, and is it part of the service charge?
Then look at what the flat service charge in Dhaka pays for. If insurance is included, ask to see the policy schedule. If it isn't, don't assume someone else has it covered.
A building-level policy generally does not protect your own belongings or the interior finishes you installed. Confirm with the insurer and the association, as the wording differs.
Even where a common policy exists, you may still need your own flat policy for contents and for your own interior fit-out.
PDL has completed 300+ projects since 1983, and it builds each one with this shared-risk question in mind. You can see how we plan the structure in PDL's construction process.
A well-built building lowers risk. It never replaces a policy.
How Much Should You Insure For?
Set your sum insured to the cost of rebuilding your flat, not what the flat would sell for. The sum insured is the most your policy will ever pay.
There are two ways to value a property. Market value is what it is worth today, after age and wear. Reinstatement value is the cost to replace it with a new equivalent, with no deduction for age.
For homes, reinstatement value is the safer choice, because it lets you rebuild without a shortfall.
For a flat, this creates a trap. The market price of a flat includes land share, location and demand. The rebuild or repair cost covers only construction and finishes.
These are different numbers, and insurers generally ask for the second one. Confirm with your insurer which figure it uses.
Why underinsuring shrinks your payout
Underinsurance means your sum insured is less than your property is actually worth.
When that happens, many insurers pay only a share of any loss. For example, stock worth 50 lakh Taka is insured for 25 lakh, which is half its value.
A 10 lakh Taka loss then pays only 5 lakh. The same logic applies to a flat. If you insure your interior fit-out for half its replacement cost, expect to receive only about half of any partial loss.
This is a general insurance rule, so ask your insurer how it applies it before you buy. For contents, walk through each room and list what you own, and keep purchase invoices and photos with the list.
If you renovate later, raise the sum insured, because new fittings cost more to replace.
What Decides the Price of Your Flat Insurance?
Three things set your premium. They are the sum insured, the perils you add, and the class of your building, and 15% VAT then lands on top.
Knowing this lets you question a quote line by line.
According to Pragati Insurance's fire insurance page, the premium equals the sum insured multiplied by a rate from the Fire Tariff, plus 15% VAT on the premium.
The same page says the rate depends mainly on the risk you cover and its nature. It also says extra perils such as riot and strike damage, cyclone, flood and explosion cost an additional premium.
The Financial Express reports that the government collects VAT at 15 percent on insurance premiums.
Reliance Insurance says a traditional fire policy covers only fire and lightning, and its premium is set by the tariff rate (the standard price list of rates for each type of building and risk) prescribed by the Central Rating Committee. Because the tariff sets the base rate, the premium for fire alone may look similar across insurers.
The differences show up in add-ons, service, and claim handling, so verify this with each insurer.
Building class matters too. Buildings fall into four main construction classes for fire insurance, and rates vary by class, by occupancy, and by the extra perils you add.
A cheap premium from the wrong class carries high risk, and a sum insured that does not match the real risk means you recover only a fraction of a loss. Ask which class your building sits in and why.
How Does a Fire Claim Work, Step by Step?
A claim moves in a fixed order. The insurer registers the claim, a surveyor investigates, and payment follows once the insurer verifies your documents.
The fire insurance claim process in Bangladesh usually looks like this. Steps can differ slightly between insurers.
- Get everyone out and call 999. Safety comes first. Once the fire is out and the area is safe, protect what survived, for example by covering undamaged items.
- Notify your insurer in writing within 24 to 48 hours. Include your name, policy number, the date, time, and location of the fire, and a short description of the damage.
This opens the claim, and the insurer can assign a surveyor.
- Get the police GD and the Fire Service report. File a General Diary entry at the local police station, and request the report from the Fire Service and Civil Defense.
Without the Fire Service report, processing a fire claim is very difficult.
- Let the surveyor inspect before you clean up. The insurer appoints an IDRA-licensed independent surveyor to look at the cause and extent of the loss.
Don't clear debris, throw out damaged items, or start repairs first.
- Submit your proof. This includes the policy, ownership documents, photos and video, purchase invoices, and repair quotes.
Keep your property registration documents in a safe second location, because they prove ownership.
- Review the settlement offer. The surveyor sends a loss assessment report to the insurer, which then makes an offer.
If you accept, you sign a discharge voucher and payment follows by cheque or bank transfer. Read the offer before signing, because the settlement is then final.
Under the Insurance Act 2010, insurers in Bangladesh must settle a general insurance claim, including fire claims, within 90 days of receiving all required documents.
The clock starts only when your file is complete, so your own speed and paperwork affect it. A fire claim usually needs a copy of the GD entry and the Fire Service report, along with proof of ownership and loss.
How to Get Quotes You Can Compare Fairly
Ask every insurer for the same things, and ask for them in writing. That is the only way to compare quotes fairly. Send each insurer this list.
- Fire plus earthquake plus flood, named explicitly.
- Structure and contents, each with its own sum insured.
- The exclusions list, in writing.
- The basis of valuation, reinstatement or market value.
- Whether theft or burglary is available, and under what conditions.
- Who pays the claim and how long settlement usually takes.
- The premium is broken into sum insured, rate, VAT, and total.
PDL puts every cost in writing for its buyers, so we hold insurers to the same standard. A quote with no written exclusions is not a quote you can trust.
Insurers with published products
These are examples, not recommendations.
Eastland Insurance has a dedicated flat/apartment owner insurance page with an online premium calculator. You choose your district, your location (city corporation or mofussil), and your total sum insured, then tick the risks you want covered. The risk options include:
- Fire
- Earthquake
- Flood
- Cyclone
- Riot and strike damage (RSD)
- Burglary
Pragati Insurance publishes a fire insurance page outlining its add-on perils and premium formula.
Compare quotes on the exclusions as well as the price. A cheaper policy that excludes flood or earthquake coverage is not really cheaper.
Which Mistakes Cost Flat Owners the Most?
Most costly mistakes come from skipping a step, not from bad luck. Seven errors show up again and again. Avoid them, and your claim has a much better chance of being paid in full.
- Insuring contents only. Your furniture is covered, but the flat's own fittings and finishes are not.
- Skipping the earthquake add-on. Dhaka is a densely built city, and planners and disaster experts regularly discuss the risk of a major earthquake. A basic fire policy does not respond to it.
- Setting a low sum insured. It lowers the premium and proportionally shrinks the payout.
- Never reading the exclusions. Willful negligence, ordinary wear and tear, and theft during a fire are examples of losses standard policies don't cover.
- Keeping records only inside the flat. If your invoices burn with the flat, proving the loss becomes harder. Keep copies in the cloud or at another address.
- Cleaning up before the surveyor arrives. Changing the scene can reduce your verified loss.
- Waiting weeks to report. Notify the insurer within 24 to 48 hours.
Your Next Step: Name the Perils, Read the Exclusions
Flat insurance is cheap protection against a rare but expensive event, and fire is not rare in Bangladesh's homes.
Ask for fire, earthquake, and flood by name, for the structure and the contents, and get the exclusions in writing. Then store the policy and your inventory somewhere a fire can't reach.
If you are buying a new apartment, raise insurance at handover. Our flat handover checklist gives you the other items to review that day.
Ask the developer or owners' association whether a building policy exists, what it covers, and how it is paid for.
PDL has built in Bangladesh since 1983 and stays in touch with owners after handover, so these are questions we want you to ask.
See our current projects, or call PDL Real Estate at 105 Pragati Sarani, Middle Badda, Dhaka, on 01704 155 555 for questions about handover.
A policy costs little on an ordinary day, and it is worth everything on the worst one.
Common Questions About Flat Insurance in Bangladesh
Does fire insurance cover earthquake?
Not on its own. A basic fire policy covers fire, lightning, and usually domestic explosion, so earthquake needs an add-on written into your schedule.
Does it cover flood or cyclone?
No, not in the basic policy. Both are add-ons that cost extra premium.
Is flat insurance mandatory?
Not for a cash buyer, but you carry the whole loss if there’s a fire. A loan buyer often has to insure, because banks commonly require it on a home loan.
Does the developer insure my flat?
Not automatically. Ask the developer or owners’ association whether a building policy exists. It generally won’t cover your belongings or the interior finishes you installed.
Are my belongings covered?
Only if you insure contents, with their own sum insured and a written inventory.
What documents do I need for a claim?
Your policy, ownership documents, photos and video, purchase invoices and repair quotes, plus the police GD entry and the Fire Service report. Tell your insurer in writing as soon as possible.